The Bond Market Pullback and Manager Sentiment
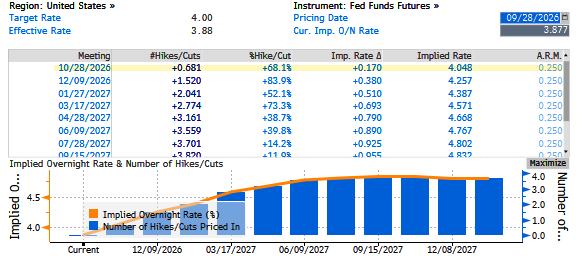
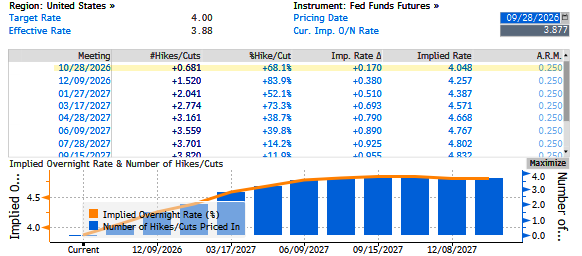
The fixed-income market is in the midst of a sell-off, yet a notable shift in tone has emerged among professional money managers. Rather than encouraging clients to flee bonds in response to falling prices, many are actively urging them to give the asset class another chance. This advisory posture reflects a broader conviction within the industry that the current dislocation represents an opportunity rather than a structural warning.
The 60-40 Portfolio's Long-Awaited Redemption
At the heart of this sentiment is the performance of the classic 60-40 portfolio — a blend of roughly 60 percent equities and 40 percent bonds that has served as the default allocation model for a generation of institutional and retail investors. According to the reporting, that combination is finally doing what it was engineered to do: cushioning equity drawdowns and smoothing overall returns. Importantly, this is being described as the first time in years the two asset classes have behaved in a genuinely offsetting manner, suggesting that the negative correlation between stocks and bonds that underpins the strategy's logic has temporarily reasserted itself.
Analytical Takeaways for Investors
From an analytic perspective, several implications deserve attention. First, the fact that managers are framing the bond sell-off as a buying opportunity rather than a risk signal suggests they view current valuations as stretched relative to forward yield expectations. Second, the 60-40 portfolio's recent diversification benefit carries a caveat: it is a snapshot of a specific market regime, not a guarantee that the stock-bond correlation will remain negative going forward. Investors who have spent the past few years watching both asset classes fall in unison may be reluctant to re-engage with bonds at the first sign of a pullback.
That said, the managers' collective nudge toward fixed income underscores a practical risk-management point. A portfolio concentrated entirely in equities forfeits the ballast that bonds provide during equity corrections, and the recent episode — however brief — demonstrates that ballast in action. For investors evaluating their allocations, the analytic question is less whether bonds will be a permanent hedge and more whether the current pricing, set against prevailing rates and inflation expectations, offers a favorable risk-reward entry relative to alternatives.