The Burger That Doubled in Price
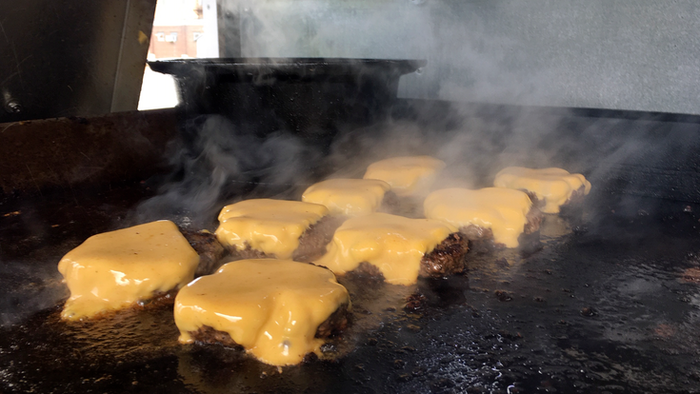
Le Diplomate, one of Washington, D.C.'s most demanding dining rooms, has become an unlikely barometer of inflation. When the restaurant opened in 2013, its signature Burger Americain—served with French fries—carried a $14 price tag, as the Washington Post noted at the time. Thirteen years on, that same plate now costs $29. The spread is not an isolated anomaly. In Texas, barbecue joints are quietly pulling brisket off their menus because the cost of the meat has become unsustainable. At Five Guys, a basic "Little Cheeseburger" now runs above $10 before you even add a side of fries.
The Conventional Explanation and Its Limits
Washington Post reporters Tim Carman and Federica Cocca attribute the spike primarily to drought conditions that have thinned domestic cattle herds. They add that the resulting supply gap has pushed importers to source more beef from overseas, with the wholesale price of imported beef climbing from $4.96 per pound in June 2025 to $5.59 per pound in June 2026—roughly a 13 percent jump in a single year. Ground beef wholesale prices, they note, have surged between 18 and 30 percent over the past several years.
The policy response from the current administration, as Carman and Cocca describe it, has been twofold: antitrust threats aimed at major domestic beef producers and a rollback of certain tariffs. The author of the source piece, RealClearMarkets editor John Tamny, dismisses the antitrust angle as counterproductive and views the tariff reduction as symptomatic of a broader economic-policy gap within the modern Republican establishment. He also pushes back on the supply-chain narrative itself, arguing that globalization and the division of labor have historically been cost-reducing mechanisms rather than cost-accelerating ones.
The Variable That Almost Nobody Tracks
Tamny's central argument is that analysts, politicians, and financial commentators obsess over the price of goods while almost entirely ignoring the unit of account in which those goods are denominated. The dollar, he stresses, is not a fixed measure the way a foot is always twelve inches or a pound is always sixteen ounces. Since the currency was floated in 1971, its value has swung meaningfully across administrations—depreciating sharply under Nixon and Carter, appreciating under Reagan and Clinton, and sliding again under George W. Bush, Obama, and now Trump.
The data he cites are specific. On the WSJ Dollar Index, the U.S. dollar has lost roughly 6.3 percent of its value against a basket of foreign currencies since Trump's inauguration in January 2025. The gold price tells a starker story: the yellow metal is up approximately 63 percent over the same period and more than 205 percent since 2013, the year Le Diplomate first priced its cheeseburger at $14. Gold's relative stability makes it a useful mirror: when the dollar weakens, gold's dollar-denominated price rises, and commodity markets react in the opposite direction.
What a Stable Dollar Would Change
The analytic takeaway is straightforward. Commodities—beef, energy, raw materials—are priced in dollars and are highly sensitive to the currency's trajectory. A depreciating dollar makes every imported input, every globally traded commodity, and every dollar-denominated obligation more expensive in real purchasing-power terms. The result is not a mysterious supply shock but a monetary one dressed up as a market phenomenon.
Tamny's plea is therefore not to fix the cattle supply or to threaten packers with antitrust suits, but to restore the dollar's purchasing power. He pushes back directly against the administration's framing of a weak dollar as beneficial, arguing that the rising cost of a cheeseburger, a brisket sandwich, or a gallon of gasoline is not a sign of a thriving economy but of a currency losing its anchor. For traders and investors tracking commodity-linked positions, the implication is that a sustained dollar decline will keep feeding into input costs across the board, making inflation a persistent feature rather than a transitory one.
Tamny, who also serves as president of the Parkview Institute, senior fellow at the Market Institute, and senior economic adviser to Applied Finance Advisors, has explored related themes in his latest book, The Deficit Delusion: Why Everything Left, Right and Supply Side Tell You About the National Debt Is Wrong.